


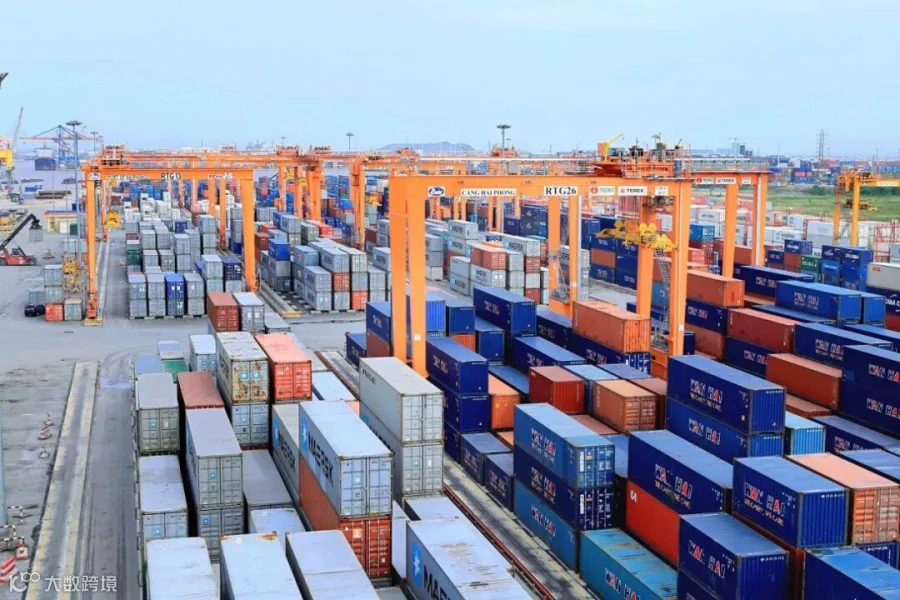
外国贸易商从越南企业购买货物,指定卖方直接交给越南境内的另一家企业,货物不必运出越南。这就是“就地进出口”,可节省运输时间和物流成本。过去,只有在越南没有“商业存在”的外国贸易商,才能采用这一方式。2025年8月15日,第167/2025/ND-CP号法令生效,取消了这一限制,扩大了制度适用范围,为交易安排提供了更多灵活性。
A foreign trader purchases goods from a Vietnamese enterprise and instructs the seller to deliver them directly to another enterprise in Vietnam, without the goods leaving the country. This arrangement, known as “on-the-spot import and export,” can shorten transportation time and reduce logistics costs. Previously, only foreign traders with no “commercial presence” in Vietnam could use this arrangement. Decree No. 167/2025/ND-CP, which took effect on 15 August 2025, removed this restriction, broadening the scope of the mechanism and providing greater flexibility in structuring transactions.
引言
Introduction
就地进出口(“OSIE”),是指外国贸易商向越南企业购买货物后,指定卖方直接将货物交给越南境内的另一家企业。整个过程中,货物都留在越南境内,无须运出越南再运回。不过,货物没有实际跨境,并不意味着可以省去海关手续。根据第54/2014/QH13号《海关法》(2025年修订)第47a条,这类交易仍须按规定办理海关手续,接受海关检查与监管,并遵守进出口管理及其他相关规定。
On-the-spot import and export (“OSIE”) is a specific form of international commercial transaction whereby goods are delivered and received within the territory of Vietnam without being physically transported out of or into Vietnam. Nevertheless, OSIE activities must still be carried out in compliance with regulations on customs procedures, be subject to customs inspection and supervision, and comply with regulations on import and export as well as other relevant regulations, pursuant to Article 47a of the Law on Customs No. 54/2014/QH13 (as amended in 2025).
通过就地进出口,卖方可以按照外国贸易商的要求,将货物直接交给越南境内的指定收货方,省去先运出越南、再运回越南的环节。这样既能缩短交货时间,减少中间环节和运输费用,也能降低货物在运输途中丢失或损坏的风险,让企业更高效地安排生产和供货。在满足相关法定条件、备齐所需单证的前提下,企业还可以享受适用于这类交易货物的税收优惠。
The application of OSIE procedures facilitates the direct delivery and receipt of goods between the seller and the recipient in Vietnam, as designated by the foreign trader, without the need to transport the goods out of and subsequently back into the territory of Vietnam. As a result, enterprises can avoid additional intermediary costs, shorten delivery and receipt times, reduce the risks of loss or damage to goods and transportation costs, improve supply chain management efficiency, and take advantage of tax incentives applicable to goods involved in OSIE transactions, provided that all statutory conditions and documentary requirements are fully satisfied.
01
法律背景
Legal background
多年来,就地进出口活动一直受2015年1月21日颁布的第08/2015/ND-CP号法令规制。根据该法令第35条第1款c项(“C项”),越南企业与外国组织或个人之间的货物买卖,必须满足以下条件,方可被认定为就地出口:
外国组织或个人与越南企业订立货物买卖合同。外国组织或个人为货物买方,越南企业为卖方。
买方(外国商人)不直接接收货物,而是指示卖方(越南企业)按照就地出口程序,将货物交付给越南境内的另一家企业。
外国商人只有在越南没有商业存在的情况下,方可进行上述交易。
For many years, OSIE activities have been governed by Decree No. 08/2015/ND-CP dated 21 January 2015. Pursuant to Point c, Clause 1, Article 35 of this Decree (“Point C”), the sale and purchase of goods between Vietnamese enterprises and foreign organizations or individuals must satisfy the following conditions to qualify as on-the-spot export:
The foreign organization or individual enters into a sale and purchase contract with a Vietnamese enterprise. The foreign organization or individual is the purchaser of the goods, while the Vietnamese enterprise is the seller.
The purchaser (the foreign trader) does not receive the goods directly but instead instructs the seller (the Vietnamese enterprise) to deliver the goods to a different enterprise in Vietnam, in accordance with on-the-spot export procedures.
The foreign trader may only carry out the aforementioned transaction if it has no commercial presence in Vietnam.
按照此前的规定,越南企业要办理就地出口,与其交易的外国贸易商必须在越南没有“商业存在”。为确认这一条件得到满足,部分地区的海关机关会依据2017年6月12日颁布的第05/2017/QH14号《外贸管理法》第3条第5款,要求外国贸易商提交书面承诺,确认其在越南没有商业存在。但在实际操作中,即使提交了承诺书,交易也未必能顺利进行。海关程序改革过程中,一些法律规定如何理解、相关手续如何办理等问题仍未得到妥善解决,给越南企业及其外国交易方都带来了困难。
Accordingly, under the previous regulations, a Vietnamese enterprise was only permitted to conduct on-the-spot exports when its foreign counterparty had no commercial presence in Vietnam. This was a mandatory condition, which led customs authorities in certain localities to require foreign counterparties to provide a Written Undertaking confirming their status in this regard, in accordance with Clause 5, Article 3 of the Law on Foreign Trade Management No. 05/2017/QH14 dated 12 June 2017 (for example, an undertaking confirming that the foreign trader “has no commercial presence in Vietnam”). In practice, even where such a Written Undertaking was provided, on-the-spot exports continued to face various inadequacies and difficulties, affecting not only Vietnamese enterprises but also their foreign counterparts, due to certain legal and practical issues arising during the reform of customs procedures.
02
法律改革
Legal reforms
然而,自第167/2025/ND-CP号法令于2025年8月15日生效后,第08/2015/ND-CP号法令第35条经修订补充,C项被废止,从而取消了以下要求:就地进出口货物必须是在越南企业与在越南没有商业存在的外国组织或个人之间交易的货物。
However, since 15 August 2025, when Decree No. 167/2025/ND-CP came into effect, Article 35 of Decree No. 08/2015/ND-CP has been amended and supplemented to abolish Point C, thereby removing the requirement that goods subject to on-the-spot import and export must be goods traded between Vietnamese enterprises and foreign organizations or individuals having no commercial presence in Vietnam.
根据现行规定,外国组织或个人是否在越南具有商业存在,已不再是交易适用就地进出口程序的条件。
Under the current regulations, whether a foreign organization or individual has a commercial presence in Vietnam is no longer a condition for a transaction to qualify for OSIE procedures.
这一变化扩大了就地进出口的适用范围,减少了办理相关手续时的障碍,让越南企业与外国贸易商在越南开展交易更加便利。越南政府也将这项调整列为海关程序改革的措施之一,以便利企业经营,降低企业遵守相关规定所需的成本。
This represents a significant change from the previous approach and contributes to expanding the scope of application of OSIE procedures, reducing procedural barriers, and facilitating Vietnamese enterprises and foreign traders in conducting transactions in Vietnam. The Vietnamese Government has also identified this as one of the measures aimed at reforming customs procedures, facilitating business activities, and reducing compliance costs.
因此,判断一笔交易能否采用就地进出口方式,已不再要求外国贸易商“在越南没有商业存在”。企业需要先确认交易涉及的货物是否属于现行规定允许就地进出口的范围,再核查合同和交付、收货指示是否符合要求,并按规定办理海关申报,接受海关检查与监管。
Accordingly, when analyzing an OSIE transaction at the present time, the requirement that the foreign trader “has no commercial presence in Vietnam” is no longer an applicable condition. Instead, it is necessary to determine whether the transaction falls within the categories of goods eligible for OSIE under the current regulations, while also examining the applicable requirements concerning contracts, delivery and receipt instructions, customs declaration procedures, and customs inspection and supervision.
这一调整有助于明确就地进出口的货物范围、纳税义务和海关手续等要求,减少因规定不够清晰或解释过于宽泛而产生的分歧,让企业更清楚地了解并遵守相关规则。同时,企业也能更顺畅地与税务、海关机关沟通和办理相关事项,使交易安排更符合国际商业惯例。
This approach reflects the reform-oriented direction of narrowing the scope for ambiguous and overly broad interpretations of relevant regulations (including those concerning goods subject to OSIE, tax obligations, customs procedures, and other related matters), thereby enhancing transparency and legal certainty in the application of the law. It also facilitates more effective compliance coordination among enterprises, tax authorities, and customs authorities, while being more consistent with international commercial practices.
03
改革的意义及其对外国商人的影响Significance of the reform and its impact on foreign traders
这项改革扩大了就地进出口的适用范围,简化了相关手续,让越南企业与外国贸易商之间的交易更加便利。企业可以更灵活地安排采购和交货,减少办理手续所需的时间和成本。这也体现了越南政府持续改进海关管理、改善营商环境的政策方向,有助于提高规则的透明度和可预期性,为国际投资与贸易提供更多便利。
This represents a significant reform that contributes to expanding and simplifying the OSIE mechanism, thereby facilitating enterprises’ commercial activities. As a result, administrative procedures are streamlined, costs are reduced, and greater flexibility is afforded in transactions with foreign traders. More importantly, this reform reflects the State’s policy direction of modernizing customs procedures and establishing a transparent and business-friendly environment, thereby promoting international investment and trade.

免责声明
Disclaimer
请注意,本文不构成针对任何具体案件的全面法律意见。如遇任何相关法律问题,请咨询具备相应资质的法律专业人士。
Please note that this article does not constitute comprehensive legal advice in relation to any specific case. Should you encounter any related legal issues, please consult a qualified legal professional.
本文作者
HOANG, Nguyen Huy
BROSS & Partners律师事务所
(BROSS & Partners Law
Company Limited)
合伙人
HOANG, Nguyen Huy为越南BROSS & Partners律师事务所(BROSS & Partners Law Company Limited)合伙人,深耕外商直接投资(FDI)、银行金融、私募及公司商事法律业务,拥有14年越南头部商业银行从业背景,曾参与银行牌照设立申报工作,擅长为外资企业处理投资合规与金融类法律事宜。
Nguyen Hoang Huy is a Partner at BROSS & Partners. He specializes in FDI, banking & finance, private equity and corporate commercial law. With 14 years’ working experience at Vietnam’s top commercial bank and experience in bank license application preparation, he is adept at advising foreign investors on investment compliance and financial legal issues.
CONTACT US/ 联系我们
邮箱:lily.hang@tahota.com
电话:159 2145 5545
特别声明:
本文仅代表作者个人观点,不得视为VATA法律服务团队或其律师出具的任何形式之法律意见或建议。本公众号文章未经授权,不得转载。如需转载,请联系VATA微信公众号后台。
VATA SHANGHAI