


投资、证券相关业务,日常很难绕开美国相关证券监管,在应对客户咨询时,虽然最终都还是依赖所内所外美国律师的最终意见结论,但大部分不求甚解的情况下,我们也可以提供一般性的咨询建议。
证券、投融资最常涉及的美国证券法律如下:
| Securities Act of 1933 | 1933年证券法 |
| Securities Exchange Act of 1934 | 1934年证券交易法 |
| Trust Indenture Act of 1939 | 1939年信托契约法 |
| Investment Company Act of 1940 | 1940年投资公司法 |
| Investment Advisers Act of 1940 | 1940年投资顾问法 |
| Sarbanes-Oxley Act of 2002 | 2002年萨班斯-奥克斯利法案 |
| Dodd-Frank Wall Street Reform and Consumer Protection Act of 2010 | 2010年多德-弗兰克华尔街改革和消费者保护法 |
Jumpstart Our Business Startups Act of 2012 Rules and Regulations |
2012年 "启动我们的商业初创企业 "法案规则和条例 |
Securities Act of 1933
又被称为"truth in securities"法,涉及两个Basic Objectives基本目标: https://www.govinfo.gov/content/pkg/COMPS-1884/pdf/COMPS-1884.pdf
require that investors receive financial and other significant information concerning securities being offered for public sale; and要求投资者收到有关公开销售的证券的财务和其他重要信息;以及
prohibit deceit, misrepresentations, and other fraud in the sale of securities.禁止证券销售中的欺骗、虚假陈述和其他欺诈行为。
以下这段话可谓是整个证券法的精髓: https://www.investor.gov/introduction-investing/investing-basics/role-sec/laws-govern-securities-industry
通过注册促进证券信息披露;
证监会监管信息真实准确,但买者因知情的投资决定造成的损失不由政府承担。
"A primary means of accomplishing these goals is the disclosure of important financial information through the registration of securities. This information enables investors, not the government, to make informed judgments about whether to purchase a company's securities. While the SEC requires that the information provided be accurate, it does not guarantee it. Investors who purchase securities and suffer losses have important recovery rights if they can prove that there was incomplete or inaccurate disclosure of important information."
美国证券注册流程的指导原则是:
registration forms companies file provide essential facts while minimizing the burden and expense of complying with the law 在提供基本事实的同时,尽量减少遵守法律的负担和费用。
Registration statements and prospectuses注册报告和招股说明书在经SEC美国证监会审核过后,很快就会公开在EDGAR数据库中,包括如下信息:
| a description of the company's properties and business; | 对公司的财产和业务的描述; |
| a description of the security to be offered for sale; | 对将要出售的证券的描述; |
| information about the management of the company; and | 关于公司管理的信息;以及 |
| financial statements certified by independent accountants. | 经独立会计师认证的财务报表。 |
证券发行也容许Registration Exemption豁免注册,
主要目的是:the SEC seeks to foster capital formation by lowering the cost of offering securities to the public通过豁免许多小型发行的注册程序,SEC试图通过降低向公众发行证券的成本来促进资本形成。
最常用的有:
| private offerings to a limited number of persons or institutions; | 向有限数量的个人或机构进行的私人发行; |
| offerings of limited size; | 规模有限的发行; |
| ntrastate offerings; and | 州内发行;以及 |
| securities of municipal, state, and federal governments. | 市政府、州政府和联邦政府的证券。 |
当然,这些豁免又会牵扯到一些定义术语之间区分,如Accredited Investor和Qualified Purchaser:
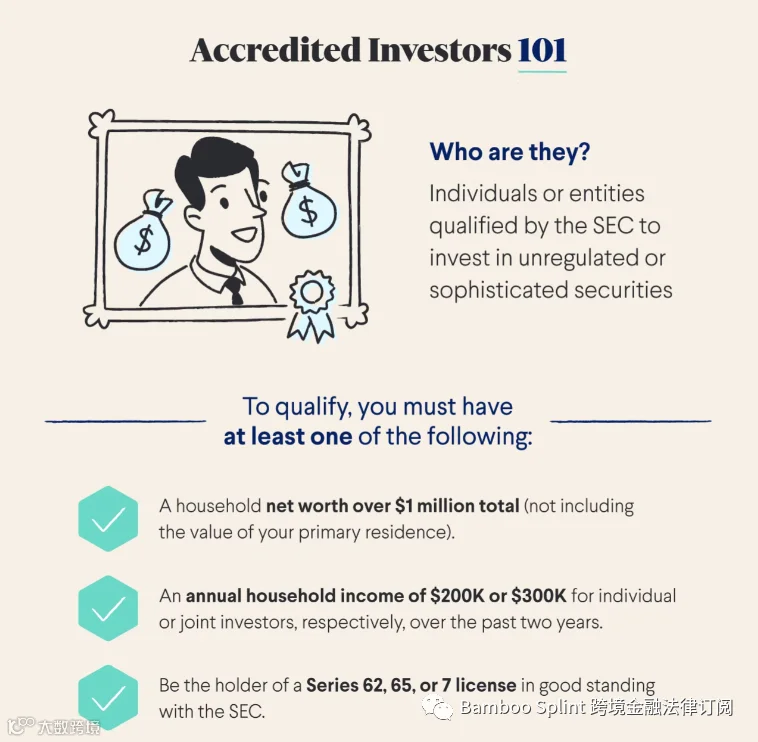
成为Accredited Investor有资信投资人,你可以不再局限于只能投资股票和公募基金,而可以分配更多的资产在Alternative Investment Structures另类投资产品上,包括VC创投基金和Hedge Fund对冲基金。值得一提的是,
在2020年时,美国有11%的家庭已认证为有资信的投资人,足见其高收入家庭的财力殷实。 https://www.investor.gov/introduction-investing/general-resources/news-alerts/alerts-bulletins/investor-bulletins/updated-3
而Qualified Purchaser 合格买家的资金实力门槛更高,因此可以接触更多投资产品,主要是Regulation D项下相关,
依据Regulation D 504、505、506发行证券, https://www.investopedia.com/terms/r/regulationd.asp
仅需递交Form D,即在EDGAR数据库公开发行人地址等极少数可查询注册信息:

| Rule 504 |
|
| allows companies to sell up to $10 million in securities in a 12-month period without registration. The company must file Form D within 15 days of the first sale. | 它允许公司在12个月内不经注册而出售高达1000万美元的证券。公司必须在第一次销售后15天内提交D表。 |
| Rule 505 |
|
In 2016, the SEC phased out Rule 505 and integrated many of its provisions into Rule 504. Previously, it allowed a company to sell up to $5 million of its securities in any 12-month period. These securities could be sold to an unlimited number of accredited investors but no more than 35 non-accredited investors. |
2016年,美国证券交易委员会逐步取消了第505条规则,并将其许多规定纳入第504条规则。 以前,它允许一家公司在任何12个月内出售最多500万美元的证券。这些证券可以出售给数量不限的认可投资者,但不超过35个非认可投资者 |
| Rule 506 |
|
As with the previous Rule 505, a company operating under Rule 506(b) may sell to an unlimited number of accredited investors and up to 35 non-accredited investors. Unlike under Rule 505, however, all non-accredited investors must be considered "sophisticated." This meany they must have enough of a financial or business background to evaluate the potential risks and rewards of the investment. If the company is selling to accredited investors, it has discretion over what company information it discloses. If it sells to non-accredited investors, though, it must follow more stringent disclosure rules, including disclosing its financial statements. |
与之前的505规则一样,根据506(b)规则运作的公司可以向数量不限的认可投资者和最多35名非认可投资者出售。然而,与505条不同的是,所有非认可投资者必须被视为 "成熟"。这意味着他们必须有足够的金融或商业背景来评估投资的潜在风险和回报。 如果公司向认可的投资者销售,它可以自行决定披露哪些公司信息。但是,如果它向非认可的投资者出售,它必须遵循更严格的披露规则,包括披露其财务报表。 |
请在评论区提出任何对本文的观点或建议,作者会尽快友善回复。
有意转载Bamboo Splint竹帚金融法律评论文章或有意愿于本订阅号投稿的朋友,欢迎联系作者:
Butler Cheng// e0724230@u.nus.edu

Vency Guo// e0724249@u.nus.edu
We'd appreciate, if you could 
我们会很感激,如果你可以 
