


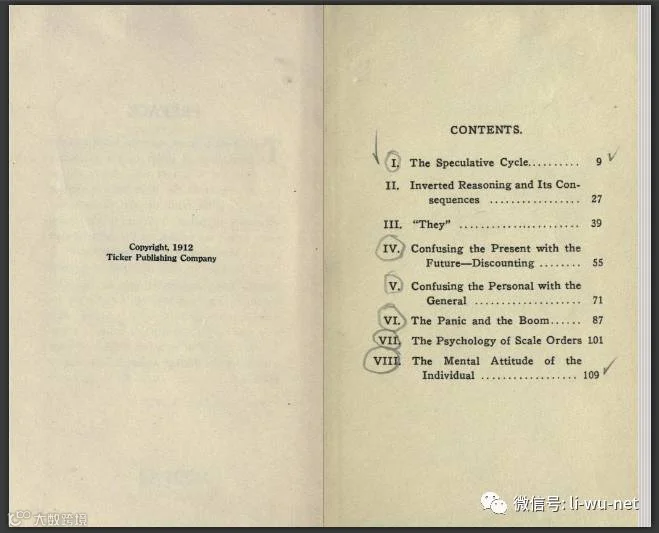
《股市心理学》Psychology of the stock market (第一二章)
《股市心理学》Psychology of the stock market (第三四章)
《股市心理学》Psychology of the stock market (第五六章)
以下为第七八章(完结):
VII The Psychology of Scale Orders
THE observer of market conditions soon comes to know that thereare two general classes of minds whose operations are reflected in prices.These classes might be named the "impulsive" and the"phlegmatic."
The "impulsive" operator says, for example, "Conditions,both fundamental and technical, warrant higher prices. Stocks are apurchase." Having formed this conclusion, he proceeds to buy. He does nottry or expect to buy at the bottom. On the contrary he is perfectly willing tobuy at the top so far, provided he sees prospects of a further advance. When heconcludes that conditions have turned bearish, or that the advance in priceshas overdiscounted previous conditions, he sells out.
The "phlegmatic" type of investor, on the other hand,can hardly ever be persuaded to buy on an advance. He reasons, "Pricesfrequently move several points against conditions, or at least against what theconditions seem to me to be. The sensible thing for me to do is to takeadvantage of these contrary movements."
Hence when he believes stocks should be bought he places an orderto buy on a scale. His thought is:
"It seems to me stocks should advance from these prices, butI am not a soothsayer, and prices have often declined three points when I feltjust as bullish as I do now. So I will place orders to buy every half pointdown for three points. These speculators are a crazy lot and there is noknowing what passing breeze might strike them that would cause a temporarydecline of a few points."
Among large capitalists, and especially in the banking community,the "phlegmatic" type naturally predominates. Such men have neitherthe time nor the disposition to watch the ticker closely and they nearly alwaysdisclaim any ability to predict the smaller movements of prices. They areentirely ready, nevertheless, to take advantage of these small fluctuationswhen they occur, and having plenty of capital, they can easily accomplish thisby buying or selling on a scale.
As a matter of fact, the market is usually full of scale orders,and the knowledge of this and of the way in which such orders are handled isdecidedly helpful in judging the tone and technical position of the market fromday to day.
The two types of operators above described are always workingagainst each other. The buying or selling of the "impulsive" tradertends to force prices up or down, while the scale orders of the"phlegmatic" class tend to oppose any movement.
For example, let us suppose that banking interests believeconditions to be fundamentally sound and that the general trend of the marketwill be upward for some time to come. Orders are therefore placed by variouspersons to buy stocks every point down, or every half, quarter, or even eighthpoint down.
On the other hand, the active floor traders find that, owing tosome temporary unfavorable development, a following can be obtained on the bearside. They perceive the presence of scale orders, but they think stocks enoughwill come out on the decline to fill the scale orders and leave a balanceover.
To put it another way, the floating supply of stocks has become,at the moment, larger than can comfortably be tossed about from hand to hand bythe in-and-out class of traders. The market must decline until a part of thisfloating supply is absorbed by the scale orders which underlie currentprices.
These conditions produce what is commonly called a"reaction." Once this surplus floating supply of stocks is absorbedby standing orders, the market is ready to start upward again.
If the general trend is upward, far less resistance will beencountered on the advance than was met on the reaction; hence prices rise to anew high level.
Then profit-taking sales will be met, on limited or scale ordersat various prices, and as the market advances the floating supply willgradually increase until it again becomes unwieldy and another reaction isnecessary.
Eventually a level is reached, or some change in conditionsappears, which causes these scale buying orders to be partially or entirelywithdrawn, and selling orders to be substituted on a scale up. The bull marketwill not go much further after this change takes place. It has now becomeeasier to produce declines than advances.
The situation is the reverse of that described above, and a bearmarket follows.
Commonly” there is a considerable period around top prices whenscale buying orders are still found on declines, but profit-taking sales arealso met on advances, so that the market is kept fluctuating withincomparatively narrow limits for a month or more. In fact, it is likely to bekept on this level so long as public buying continues greater than publicselling. This is sometimes called "distribution." A similar period of"accumulation" often occurs after a bear market has run its course,and before any important advance appears.
A close watch of transactions, or a study of continuous quotationsas published in certain newspapers, often enables the experienced trader todiscover when the most important of these scale orders are withdrawn orreversed.
A bull market which is full of scale buying orders encounters"support” so-called, on declines. Bears are timid about driving downprices, because they are continually "losing their stocks." They saythat "very little stock comes out on declines"; hence there is acertain appearance of caution in the way the market goes down, and the activityof trade shows, in a broad way, a falling off at lower prices. On the advances,however, a following is obtained and activity increases.
Toward the end of the bull market a change is noticeable. Pricesgo down easily and on larger transactions, while advances are sluggish andopposition is met at higher levels where profit-taking orders have beenplaced.
The very day when scale buying orders in a stock are withdrawn canoftentimes be distinguished.
In a bear market, "pressure" appears in place of"support." The scale orders are mostly to sell as the market rises.Only a small following of purchasers is obtainable on advances, hence theactivity of business, in a general way, falls off as prices go up.
The end of the bear market is marked by the reappearance of"support" and the removal of "pressure," so that pricesrebound quickly and sharply from declines.
The common assumption is that this "support" or"pressure" is supplied by "manipulators." But it is quiteas likely to result from the scale operations of hundreds of different persons,whose mental make-up prevents them from buying or selling in the "impulsive"way.
VIII The Mental Attitude of the Individual
IN previous chapters we have seen that many, if not most, of theeccentricities of speculative markets, commonly charged to manipulation, are infact due to the peculiar psychological conditions which surround such markets.Especially, and more than all else together, these erratic fluctuations are theresult of the efforts of traders to operate, not on the basis of facts, nor ontheir own judgment as to the effect of facts on prices, but on what theybelieve will be the probable effect of facts or rumors on the minds of othertraders. This mental attitude opens up a broad field of conjecture, which isnot limited by any definite boundaries of fact or common sense.
Yet it would be foolish to assert that assuming a position in themarket based on what others will do is a wrong attitude. It is confusing to theuninitiated, and first efforts to work on such a plan are almost certain to bedisastrous; but for the experienced it be- comes a successful, though of coursenever a certain, method. A child's first efforts to use a sharp tool are likelyto result in bloodshed, but the same tool may trace an exquisite carving in thehands of an expert.
What, then, should be the mental attitude of the intelligent buyerand seller of securities?
The "long pull" investor, buying outright for cash andholding for a liberal profit, need only consider this matter enough to guardagainst becoming con- fused by the vagaries of public sentiment or by his owninverted reasoning processes. He will get the best results by keeping his eyesingle to two things: Facts and Prices. The current rate of interest, theearning power of the corporations whose stocks he buys, the development ofpolitical conditions as affecting invested capital, and the relation of currentprices to the situation as shown by these three factors these constitute themost important food for his mind to work upon.
When he finds himself wandering off into a consideration of what"They" will do next, or what effect such and such events may have onthe sentiment of speculators, he cannot do better than to bring himself up witha short turn and sternly bid himself "Back to common sense."
For the more active trader the situation is different. He need notbe entirely unregardful of values or fundamental conditions, but his primeobject is to "go with the tide." That means basing his operations toa great extent on what others will think and do. His own mental attitute, then,is a most important part of his equipment for success.
First, the trader must be a reasoning optimist. A more horriblefate can scarcely be imagined than the shallow pessimism of many markethabitues, whose minds, incapable of grasping the larger forces beneath themovements of prices, take refuge in a cynical disbelief in pretty much everythingthat makes life worth living.
Owing to the nature of the business, however, this optimism mustbe of a somewhat different character from that which brings success in otherlines. As a general thing optimism includes the persistent nourishing of hope,an aggressive confidence, the certainty that you are right, a firmdetermination to accomplish your end. But you cannot make the stock market moveyour way by believing that it will do so. Here is one case, at any rate, whereNew Thought methods cannot be directly applied.
In the market you are nothing but a chip on the tide of events.Optimism, then, must consist in believing, not that the tide will continuallyflow your way, but that you will succeed in floating with the tide. Youroptimism must be, in a sense, of the intellect, not of the will. An optimismbased on determination would, in this case, amount to stubbornness.
Another quality that makes for success in nearly every line ofbusiness is enthusiasm. For this you have absolutely no use in the stockmarket. The moment you permit yourself to become enthusiastic, you aresubordinating your reasoning powers to your beliefs or desires.
Enthusiasm helps you influence other men's minds, but in themarket you do not desire to do this (unless you happen to be a big bullleader). You wish to keep your mind as clear, cool and unruffled as the surfaceof a mountain lake on a calm day. Any emotion enthusiasm, fear, anger,depression will only cloud the intellect.
Doubtless it would be axiomatic to warn the trader againststubbornness.
It cannot be assumed that any operator would consciously permithimself to become stubborn. The trouble arises in drawing the line between, onthe one hand, persistence, consistence, pursuit of a definite plan untilconditions change; and, on the other, stubborn adherence to a course of actionwhich subsequent events have proved to be erroneous.
A day in the country, with the market forgotten, or if necessaryforcibly ejected from the thoughts, will often enable the trader to return witha clarified mind, so that he can then intelligently convict or acquit himselfof the vice of stubbornness. Sometimes it may become necessary to close allcommitments and remain out of the market for a few days.
One of the most common errors might be described as "gettinga notion." This is due to the failure or inability of the trader to take abroad view of the entire situation. Some particular point in the complexconditions which usually control prices, appeals to him strongly and impresseshim as certain to have its effect on the market. He acts on this singleidea,
The idea may be all right, but other counterbalancing factors mayprevent it from having its natural effect.
You encounter these "notions" every day in the Street.You meet a highly conservative individual and ask him what he thinks of thesituation. "I am alarmed at the rapid spread of radical sentiment” hereplies. " How can we expect capital to branch out into new enterpriseswhen the profits may be swept away at any moment by socialisticlegislation?"
You say mildly that the crops are good, the banking situationsound, business active, etc. But all this produces no impression upon him. Hehas sold all his stocks and has his money in the banks. (He is also short aconsiderable line, but he doesn't tell you this). He will not buy again untilthe public becomes "sane."
The next man you talk with says: "We cannot have much declinewith the present good crop prospect. Crops lie at the basis of everything. Withnine billions of new wealth coming out of the ground and flowing into thechannels of trade, we are bound to have prosperous conditions for some time tocome."
You speak of radicalism, adverse legislation, high cost of living,etc.; but he thinks these are relatively unimportant compared with that$9,000,000,000 of new wealth. Of course, he is long of stocks.
"To make the worse appear the better reason," said Mr.Socrates, some little time ago. It is too bad we can't have Socrates' commentson Wall Street. The Socratic method applied to the average speculator wouldproduce amusing results.
Beware of saying, "This is the most important factor in thesituation," unless the action of the market shows that others agree withyou. Every human mind has its own peculiarities, so presumably yours has,though you can't see them plainly; but the stock market is the meeting of manyminds, having every imaginable peculiarity.
However important some single factor in the situation may appearto you, it is not going to control the movement of prices regardless ofeverything else.
An exaggerated example of "getting a notion" is seen inthe so-called "hunch." This term appears to mean, when it meansanything, a sort of sudden welling up of instinct so strong as to induce thetrader to follow it regardless of reason. In many cases, the "hunch"is nothing more than a strong impulse.
Almost any business man will say at times, "I have a feelingthat we ought not to do this," or "Somehow I don't like thatproposition," without being able to explain clearly the grounds for hisopposition. Likewise the "hunch" of a man who has watched the stockmarket for half a lifetime may not be without value. In such a case itdoubtless represents an accumulation of small indications, each so trifling orso evasive that the trader cannot clearly marshal and review them even in hisown mind.
Only the experienced trader is entitled to a "hunch."The novice, or the man who is not closely in touch with technical conditions,is merely making an unusual ass of himself when he talks about a"hunch."
The successful trader gradually learns to study his own psychologicalcharacteristics and allow to some extent for his customary errors of judgment.If he finds that he is generally too hasty in reaching a conclusion, he learnsto wait and reflect further.
After making his decision, he withdraws it and lays it up on ashelf to ripen. He makes only a part of his full commitment at the moment whenhe feels most confident, holding the remainder in reserve.
If he finds that he is usually overcautious, he eventually learnsto be a little more daring, to buy a part of his line while his mind is stillpartially enveloped in the mists of doubt.
Most of the practical suggestions which can be offered arenecessarily of a somewhat negative character. We can point out the errors to beavoided much more successfully than we can lay out a course of positive action.But the following summary may be useful to the active trader:
(1) Your main purpose must be to keep the mind clear and wellbalanced.
Hence, do not act hastily on apparently sensational information;do not trade so heavily as to become anxious; and do not permit yourself to beinfluenced by your position in the market.
(2) Act on your own judgment, or else act absolutely and entirelyon the judgment of another, regardless of your own opinion. "Too manycooks spoil the broth."
(3) When in doubt, keep out of the market. Delays cost less thanlosses.
(4) Endeavor to catch the trend of sentiment. Even if this shouldbe temporarily against fundamental conditions, it is nevertheless unprofitableto oppose it.
(5) The greatest fault of ninety-nine out of one hundred activetraders is being bullish at high prices and bearish at low prices. Therefore,refuse to follow the market beyond what you consider a reasonable climax, nomatter how large the possible profits that you may appear to be losing byinaction.
The field covered by these chapters is to a great extent new. Asit becomes more thoroughly cultivated, it may be possible to speak with more scientificdefiniteness. In the meantime, the author hopes that his comments andsuggestions may be of some service in helping readers to avoid unwise risks andto apply sound principles of analysis to the investment or speculativesituation.
THE MAGAZINE OF WALL STREET
Articles by practical authoritative writers discuss eachmonth:
Business and Investment Conditions the future, not the past.
Fundamental Statistics as they bear upon financialconditions.
Special Opportunities in Bonds pointed out by a well-knownexpert.
Bargains in Stocks as indicated by earning power.
Railroad and Industrial Reports analyzed and interpreted.
Digest of Investment News condensed from all authenticsources.
The Market Outlook factors beneath the surface of currentevents.
Cotton and Grain articles by practical students of thesituation.
Inquiries a suggestive department of answers by conservativeauthorities.
Dividend Calendar showing in advance when books close.
Scientific Methods of Investment explained in specialarticles.
Analyses of Trader's Accounts, etc. showing right and wrongmethods.
25c. a Copy $3.00 a Year
TICKER PUBLISHING COMPANY
2 Rector St., New York
14 METHODS OF OPERATING IN THE STOCK MARKET
Contains Some of the Best Ideas Printed in The Magazine of WallStreet
Bound in Leather, $1.00 Postpaid
The tried and tested methods of market experts are here collectedfor the first time.
CONTENTS : PRINCIPLES OP PRICE
MOVEMENTS; the fundamental basis of market changes, by Thos. F.Woodlock,
Member N. Y. Stock Exchange A SCALE PLAN ; recommended by Chas. H.Dow, formerly of Dow, Jones & Co. METHODS OP FORECASTING THE MARKET; byRoger W. Babson, the eminent statistician TAKING AN INVESTMENT POSITION; byHenry Hall, the prominent financial writer THE STUDY OP VOLUMES; practicalmethods of applying recognized stock market principles
A SIGN OP BULL MOVES; a principle which shows when stocks arescarce A STOP ORDER METHOD; successfully used by an ex- perienced trader HOW TOJUDGE THE MARKET FROM THE TAPE; by "Rollo Tape" A SUCCESSFUL ACCOUNT;from small capital and sound methods METHOD OF FORECASTING A GREAT RISE HOW ASMALL TRADER BUILT UP A FORTUNE WHEN TO BUY BANKRUPT STOCKS.
Illustrated with charts and diagrams.
Pocket size.
The Magazine of Wall Street
(formerly The Ticker and Investment Digest)
2 Rector St. New York
The Most Important Factor in Trading or Investing is a Knowledgeof The Trend
It is better to know which way the general market is likely toswing than to know earnings, dividends or fundamentals.
The tape gives very definite indications as to the immediatefuture.
Our Trend Letter, written from the tape, contains thisinformation.
Issued every Thursday with additional special letters whenever achange occurs. Condensed "collect" night letter given by wire todistant subscribers without additional charge.
Write TODAY for samples, terms and record of results
Ticker Publishing Company
2 Rector Street, New York
A NEW ERIE
Read the history of this great railroad
"The Story of Erie"
By EDWARD HAROLD MOTT.
Jay Gould's manipulations his amazing genius and audacityCommodore Vanderbilt's attempt to control Erie; Daniel Drew and his printingpress; the inside stories of Manipulation; the conspiracies and corners inErie; the story of Jim Fisk; the Wall Street bouts of Drew and Vanderbilt; theBlack Friday panic all are faithfully depicted here in the most absorbingstyle. No one with a dollar's interest in Wall Street can afford to miss thisopportunity to secure one of these books. Size, 10 x 12; 524 pp.;nearly 2inches thick. Cost to mail, 45 cents. Bound in extra cloth.
Price, $1.00 net ; $1.45 postpaid
THE TICKER PUBLISHING CO.
2 Rector Street, New York
14 DAY USE
FROM WHICH BORROWED
YA 06445
U. C. BERKELEY LIBRARIES
<完>
公号回复:股市心理学
有排版好的PDF全文。